Rupiah Risks Sliding to 18,200 per US Dollar as Five Key Indicators Take Center Stage
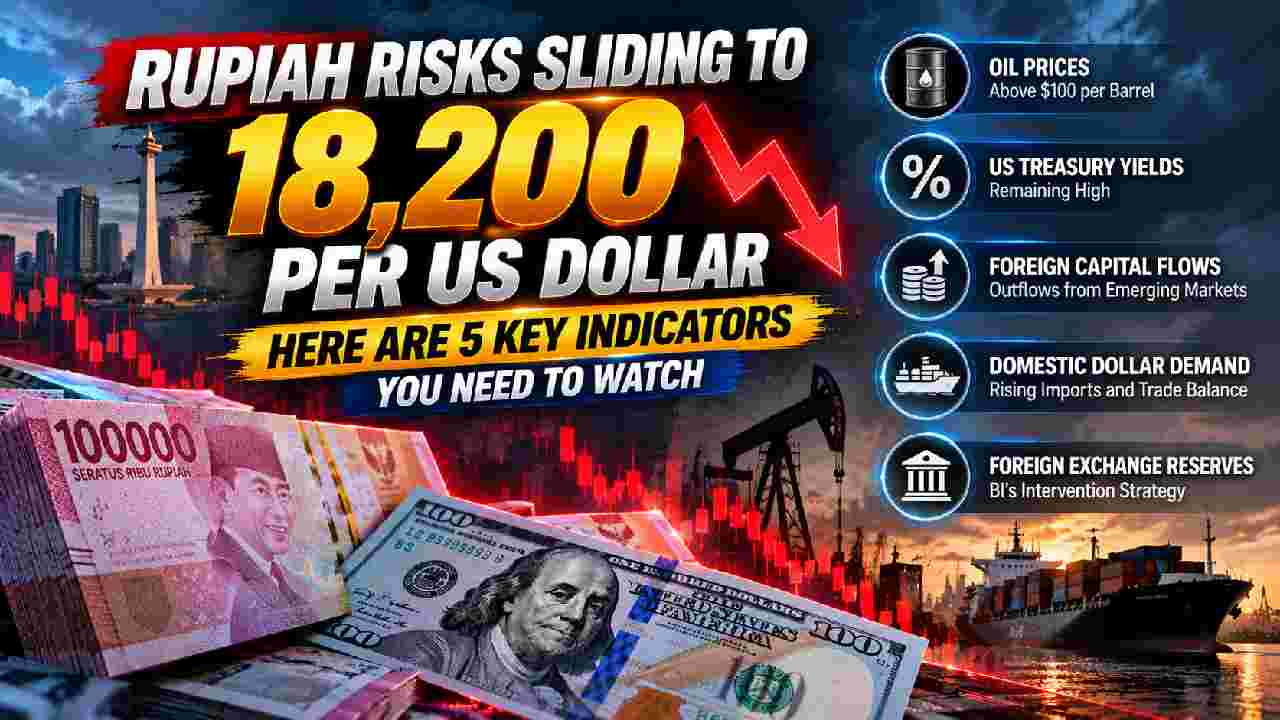
Ohana Magazine – The Indonesian rupiah is entering a sensitive period as investors watch the risk of a fall toward Rp18,200 per US dollar. The currency recently closed at Rp18,027 per dollar. It weakened by 89 points, or around 0.50 percent, from Rp17,938. However, the Rp18,000 level tells only part of the story. Several forces are now shaping the market at the same time. These include high oil prices, US Treasury yields, foreign capital flows, domestic dollar demand, and Indonesia’s foreign exchange reserves. Therefore, investors need to watch more than the exchange rate itself. The Rupiah Exchange Rate Outlook depends on whether these pressures ease or become stronger. A move toward Rp18,200 would not represent a huge percentage change. Still, it could have a strong psychological effect on investors, companies, and consumers who closely follow the rupiah.
High Oil Prices Could Increase Indonesia’s Dollar Demand
Global oil prices are the first major indicator to watch because Indonesia still depends on imported energy. Oil recently climbed above US$108 per barrel amid uncertainty surrounding the Strait of Hormuz. When oil stays above US$100, Indonesian importers may need more dollars to pay for energy purchases. As a result, higher dollar demand can place additional pressure on the rupiah. The effect could become stronger when expensive oil appears alongside foreign capital outflows. High US bond yields could add another layer of pressure. However, lower oil prices could provide some relief. Progress in geopolitical negotiations may also help reduce market concerns. Under better conditions, the rupiah could regain some lost ground. Therefore, investors should monitor Brent and WTI prices closely. Indonesia’s oil and gas imports also deserve attention because they can influence domestic demand for foreign currency.
Read More : West Bank Violence Draws Global Scrutiny After French Mayor Attacked
US Treasury Yields Keep Dollar Assets Attractive
The second indicator comes from the United States bond market. The 10-year US Treasury yield reportedly reached 5.23 percent on September 25, 2026. Earlier in the year, the benchmark yield stood near 4.15 percent. This increase matters for the Rupiah Exchange Rate Outlook. Higher US yields can make dollar assets more attractive to global investors. Therefore, some investors may reduce their exposure to emerging markets and move funds toward US assets. Such a shift can increase pressure on currencies such as the rupiah. Persistent US inflation and large Treasury issuance have also influenced market expectations. Meanwhile, investors continue to watch the Federal Reserve for signals about future interest rates. If the 10-year Treasury yield stays above 5 percent, pressure could remain. The yield gap between Indonesian government bonds and US Treasuries will also remain important for international investors.
Foreign Capital Flows Could Shape the Rupiah’s Direction
Foreign capital movement is the third important signal. When global investors sell emerging-market stocks or bonds, they often convert their funds into dollars. Consequently, this process can increase demand for the US currency and weaken the rupiah. Bank Indonesia has responded by expanding hedging support through swap transactions and domestic non-deliverable forwards, known as DNDF. According to the information provided, these measures helped attract around US$6 billion within roughly one month. Still, hedging tools cannot solve every source of currency pressure. They tend to work better when the market faces temporary dollar shortages or expensive hedging costs. Their impact may become weaker when investors expect further rupiah depreciation. For this reason, foreign activity in Indonesian stocks and government bonds remains important. A steady return of overseas capital would offer a more positive signal than a short period of inflows.
Read More : Argentina’s University Funding Crisis Spills Into Buenos Aires Streets
Domestic Dollar Demand Adds Pressure from Within Indonesia
The fourth indicator comes from domestic demand for foreign currency. Indonesian importers increased their need for dollars toward the end of the third quarter. That demand arrived when the rupiah was already facing pressure from global markets. Data cited for January to July 2026 showed exports rising 4.43 percent from a year earlier. However, imports increased much faster at 19.94 percent. Estimates for August also pointed to stronger import growth than export growth. The trade surplus was projected at around US$700 million. A smaller surplus matters because export earnings provide dollars to the domestic market. Therefore, faster import growth can reduce that support. Timing is also important. If the rupiah improves after quarter-end demand falls, some pressure may have been seasonal. However, continued weakness could suggest that broader economic forces are affecting the currency.
Foreign Exchange Reserves Give Bank Indonesia Room to Act
Indonesia’s foreign exchange reserves are the fifth key indicator. The reserves stood at US$146.5 billion at the end of August 2026. This buffer gives Bank Indonesia resources to help reduce extreme currency movements. The central bank can use offshore non-deliverable forwards, domestic spot transactions, and DNDF instruments. It can also purchase government securities in the secondary market. Meanwhile, Bank Indonesia has adjusted the way it intervenes in the market. The share of spot transactions reportedly fell to around 30 percent of total intervention. The central bank also kept the BI Rate at 5.75 percent during its September policy meeting. A rate increase remains one possible response to currency pressure. However, higher rates could also affect credit growth and economic activity. Therefore, markets will watch reserve levels, policy decisions, and the scale of future intervention.
The Path to Rp18,200 Depends on Five Signals Moving Together
A rupiah rate of Rp18,200 per US dollar remains a risk scenario rather than a certain outcome. Currency markets rarely change direction because of one factor alone. For example, oil prices could fall while US Treasury yields remain high. In that case, the benefit for the rupiah may remain limited. Likewise, Bank Indonesia can reduce short-term volatility through market intervention. However, intervention alone may not remove every source of pressure. Therefore, the five indicators should be viewed together. Lower oil prices would help, while falling US yields could improve market sentiment. Returning foreign capital would provide another positive signal. Healthy trade flows and strong foreign exchange reserves would add further support. In contrast, pressure could increase if several indicators worsen at once. Ultimately, the Rupiah Exchange Rate Outlook will depend on how global conditions, capital flows, and domestic dollar demand develop together.